
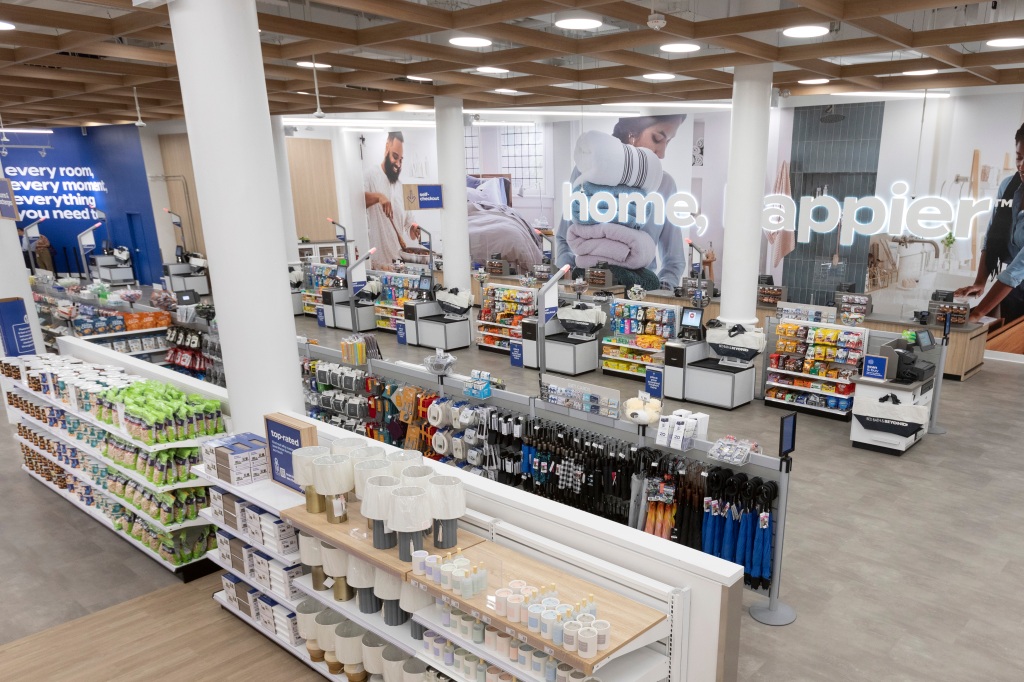
The squeeze is clearly on in retail — and companies with a history of operational missteps or balance sheets full of pandemic-era debts are succumbing to bankruptcy as shoppers pull back in a still uncertain economy. Last week, it was David’s Bridal, which had to borrow to get through COVID-19 and ran out of liquidity and is looking to emerge from bankruptcy as a going concern, although perhaps with changes to its storebase. On Sunday, it was Bed Bath & Beyond Inc., which filed for Chapter 11 protection so it could wind down operations and sell off its assets after a failed turnaround and years of lackluster performance. Bed Bath & Beyond secured roughly $240 million in debtor-in-possession financing from Sixth Street Specialty Lending to facilitate the process. The Union, New Jersey-based retailer’s 360 Bed Bath & Beyond stores and 120 Buybuy Baby stores are starting down the path to closure, although the company is also managing inventory so it can pivot should a buyer step forward in the court-run process. Sue Gove, president and chief executive officer of Bed Bath & Beyond, said, “Millions of customers have trusted us through the most important milestones in their lives — from
Read More

Thursday, October 1, 2026

Thursday, October 1, 2026
Retail Jolt: Bed Bath & Beyond Succumbs to Bankruptcy – WWD

ADVERTISEMENT
- Trending
- Comments
- Latest




We bring you the best news, updates, reviews, and events coverage surrounding the worlds top Social Network Companies.
